Listen to the podcast:
Making Aliyah is exciting, but the money side can get stressful fast: opening a bank account, funding your first months in Israel, and converting foreign currency without losing a hidden percentage along the way. This guide is written for new olim (new immigrants to Israel; oleh in singular) who want a clear plan and practical guardrails.
Nothing here is personal financial or tax advice. Use it to ask better questions, compare options, and avoid the most common (and expensive) mistakes.
What are the three money decisions you should make before you land in Israel?
Before your flight, decide (1) how you will access shekels in your first week, (2) how you will transfer larger amounts once you have an Israeli account, and (3) which documents will prove where your money came from. If you make these choices early, you avoid panic conversions at terrible rates and “compliance freezes” later.
Which documents should you pack so banks don’t block your transfers later?
Bring a “source-of-funds” folder that explains your money in plain English: bank statements, pay slips, pension statements, a home sale contract, or an inheritance letter. Israeli banks are required to ask, especially for larger transfers, and having documents ready turns a scary call into a quick email. Pack digital copies plus paper backups.
- Identity: passport, Israeli ID (Teudat Zehut) if you already have it, and your immigrant certificate (Teudat Oleh) once issued.
- Address: a lease, utility bill, or a signed letter from a host plus their proof of address if you are staying with family.
- Source of funds: recent statements and a short one-page explanation (example template later in this guide).
- Tax ID: if you are a U.S. citizen, bring your SSN and be ready for FATCA questions (FATCA is a U.S. law that makes foreign banks report certain accounts).
“Source of funds” note generator
How much cash should you bring, and when do you need to declare it?
Plan arrival cash around your actual expenses and available payment methods. Before carrying cash or other reportable instruments across a border, check the current Customs rules for that crossing and the total you are responsible for reporting.
The Tax Authority’s cash-declaration service distinguishes specified land crossings and directs Allenby travellers to a separate service. Check the current threshold, included instruments, joint ownership and filing instructions for your actual crossing before travel. Do not apply one figure to every land border or confuse a border declaration with a bank-transfer rule. Ask Customs if your reporting obligation is unclear.
A practical target is 1–2 weeks of expenses in shekels, plus a backup card. If you need more liquidity, plan an electronic transfer rather than carrying large sums.
Which accounts should you keep open abroad, and why?
Keep one primary home-country account open for at least 6 months. It covers timing gaps: delayed Israeli card approvals, a transfer that arrives in dollars before conversion, or a bank that needs extra documents. It also lets you pay leftover bills abroad while your Israeli setup stabilizes.
What is the Bank of Israel “representative rate” (shaar yatzig), and why should you check it first?
The Bank of Israel representative rate is an indicative reference, not a promised transaction rate. Compare quotes for the same amount and timing, including the exchange rate, explicit charges and expected net amount received.
Here is the key vocabulary, defined once so the rest of the guide stays simple:
- Mid-market rate: the midpoint between global buy and sell prices at a given moment.
- Spread: the gap between what a provider buys at and sells at; this gap is a hidden fee.
- Commission/fee: an explicit charge (for example, ₪25 for a conversion), sometimes layered on top of a spread.
Which exchange method usually gives new olim the best all-in rate?
Compare banks, transfer providers, cards and cash exchange for the transaction you actually need. No method is universally cheapest. Ask for the rate, all stated charges, payment timing and net shekels received before committing.
For arrival-day cash, compare the displayed exchange terms with available card or ATM charges and your immediate needs. Location alone does not establish which quote gives the best net result.
When should you use a licensed money changer instead of a bank?
For physical cash, compare current written quotes from appropriately licensed providers. A “no commission” label does not establish the best overall result; check the rate and every additional charge.
Use dealers that are properly licensed and operate transparently, especially for large sums. Israel regulates money service businesses, including foreign currency exchange and money transmission. Government of Israel
Quick quote script (money changer or bank):
- “If I exchange [amount] today in one transaction, what exact rate will I receive in ₪?”
- “Is there any fixed fee on top of that rate?”
- “Can you improve the rate if I do it all at once instead of in smaller conversions?”
When do ATMs and card payments beat cash exchange?
For cards and ATMs, check your issuer’s foreign-transaction charges, withdrawal charges and any operator fee. If offered a choice of currencies, compare the displayed conversion terms with your card’s terms; do not assume either option is always cheaper.
The convenient option depends on the amount, access, fees and conversion terms. Compare the actual total rather than applying a fixed percentage rule to every card or ATM.
How do you spot a “zero commission” trap in 30 seconds?
Ask for the exact rate and the net amount you will receive after disclosed charges. A difference from the representative rate is a comparison against that reference, not by itself proof of a hidden fee or the total cost.
Here is a simple method you can do on your phone:
-
Find the benchmark rate.
Use the Bank of Israel representative rate as a reference: Bank of Israel exchange rates - Estimate the difference from the reference:
amount × reference rate × percentage difference. This is an illustrative comparison. Add explicit charges and check the final quoted amount; the reference is not a guaranteed executable rate. -
Add any fixed fees:
bank conversion fee, ATM fee, wire fee
Example calculation (you can copy this):
- Amount: $10,000
- Benchmark: ₪3.20 per $1
- Offered rate is 1.2% worse (spread = 0.012)
- Hidden cost ≈ 10,000 × 3.20 × 0.012 = ₪384
In this illustration, ₪384 is the difference from the stated reference rate. It is not proof of an actual commission or the full transaction cost; compare the final quoted proceeds and all charges.
Break-even calculator: when does a negotiated bank deal beat a fintech fee?
If you have two options:
- Option A (bank): bank spread % plus a fixed fee (often in ₪)
- Option B (fintech): one all-in fee %
A rough break-even amount in foreign currency is:
break-even ≈ fixed_fee_₪ ÷ (benchmark_rate × (fintech_fee% − bank_spread%))
Example (using round numbers): if the fixed fee is ₪25, the benchmark is ₪3.20 per $1, the fintech fee is 0.7%, and you negotiate the bank spread down to 0.4%:
break-even ≈ 25 ÷ (3.20 × (0.007 − 0.004)) ≈ $2,600
Above that, the bank can be cheaper in theory, but only if the negotiated rate is real and the bank does not add extra charges.
Advanced note for very large conversions
If you are converting a six-figure amount, the “best” option can flip. A bank that gives you a genuinely improved FX rate (and a flat incoming-wire fee) can sometimes beat a fintech’s percentage fee, and an FX specialist may beat both. The non-negotiable rule is to compare net shekels delivered, not marketing claims.
How do you open an Israeli bank account as an oleh without surprises?
Open the account early, pick a branch that actually deals with new immigrants, and treat the first meeting like onboarding, not a transaction. Israeli banks must follow strict anti-money-laundering rules, so the easiest path is to arrive with clean documents, clear answers, and realistic expectations about credit cards and transfers. The goal is a functional account first, perks second.
How to choose a bank (and branch) without overthinking it
- Pick a branch that regularly serves English speakers and new immigrants; the branch culture matters as much as the brand.
- Compare three things in writing: monthly account plan, international transfer fees, and FX conversion policy.
- Ask how quickly you can get a debit card, and what is required to approve a credit card.
If you want a starting shortlist, many olim begin by comparing the big retail banks (Bank Leumi, Bank Hapoalim, Israel Discount Bank, Mizrahi-Tefahot, and First International Bank). Your best choice is the one that gives you the best fee plan plus a branch that answers emails.
What documents and answers do banks expect for compliance?
Expect questions in three buckets: who you are, where you live, and where your money comes from. If you answer these cleanly, everything else moves faster. Prepare to show IDs, proof of address, and the story of your funds (salary, savings, pension, property sale). Large deposits and transfers can trigger extra questions and reporting thresholds.
A practical “answer sheet” to draft in advance:
- Why are you opening the account (salary, benefits, rent, bills)?
- What is your expected monthly inflow/outflow range?
- What is the source of your initial deposit and future transfers?
Ask the receiving bank which identification and source-of-funds documents it requires for your transaction. Cash-reporting rules, cross-border declarations and checks on a bank transfer are separate matters. A particular cash threshold does not establish a universal rule for every wire transfer.
Which account settings prevent avoidable fees in year one?
Choose simplicity: a shekel (ILS) account for day-to-day life, plus a foreign-currency sub-account only if you truly need to hold dollars or euros for a specific purpose. Ask about “package” pricing (a monthly bundle that includes common actions) versus per-transaction fees, and switch as your usage stabilizes. Also ask about discounted “oleh benefits” and when they expire.
One negotiating tip that works: banks often have room to improve your FX rate for a large conversion. Even a 0.5% improvement matters at scale, and it costs you nothing to ask.
Two fee-reduction moves that are often overlooked
- Ask your bank to switch you to the right fee plan for your usage (bundled packages can be cheaper than per-action pricing).
- Do more actions in digital self-service rather than at a teller, since teller actions often cost more.
The Bank of Israel publishes public guidance on lowering account-management and card costs. Bank of Israel
How do you get a debit card, credit card, and Israeli payment tools working fast?
You will usually get a debit card first; credit cards often require income history, a guarantor, or time. If you need one quickly, ask about secured cards, adding a working spouse, or keeping a small regular deposit to build activity. For everyday transfers, set up local tools early, like bank transfers and common payment apps.
What is the smartest way to transfer money from abroad to Israel?
The smartest transfer is the one that survives compliance checks, minimizes all-in cost, and lands as usable shekels when you need them. For large sums, a traditional international wire can still be the most reliable rail, but you must budget for multiple fees and the bank’s conversion spread. For smaller or recurring transfers, transparent fintech pricing can win.
What does a SWIFT wire really cost once you include every layer?
A SWIFT wire is reliable for large sums, but the true cost is a stack: sending fee, possible intermediary deductions, Israeli receiving fee, and the bank’s FX spread when you convert to shekels. Even a small spread can cost more than all fixed fees combined, so estimate the spread cost before you send.
Obtain the receiving bank’s current tariff or written quote for the actual currency, account and transfer route. Ask separately about sending, intermediary and receiving charges; do not budget using one general percentage for all banks.
A clean way to estimate total cost is:
Total cost ≈ send fee + receive fee + (amount × FX spread)
If your bank spread is 1.5% on a $50,000 transfer, the spread alone can dwarf every fixed fee.
When do services like Wise or Revolut make sense, and what is “Masav”?
These services can win when you want an upfront fee and a rate close to mid-market, especially for recurring or mid-sized transfers. “Masav” is Israel’s domestic bank transfer system; if money lands as a local transfer, some costs can be lower than a full international wire. Always compare a live quote to your bank’s net shekel result.
How do you avoid transfer freezes and source-of-funds drama?
Before a substantial transfer, ask your bank about the intended sender, source, purpose and supporting documents. Keep consistent records, including relevant statements and sale or pension documents. Providing documents does not guarantee that a transfer will avoid review, delay or refusal.
Compare converting before sending with sending the original currency and converting after receipt. Include both banks’ or providers’ charges and the actual final amount; neither route is universally cheaper.
If you are transferring money for a home purchase or other time-sensitive deal, coordinate the transfer plan with whoever is handling the transaction (often your lawyer and the receiving bank branch). FX timing, documentation, and cut-off times can matter as much as the rate when a payment deadline is fixed.
What tax benefits do new immigrants get, and what is changing on January 1, 2026?
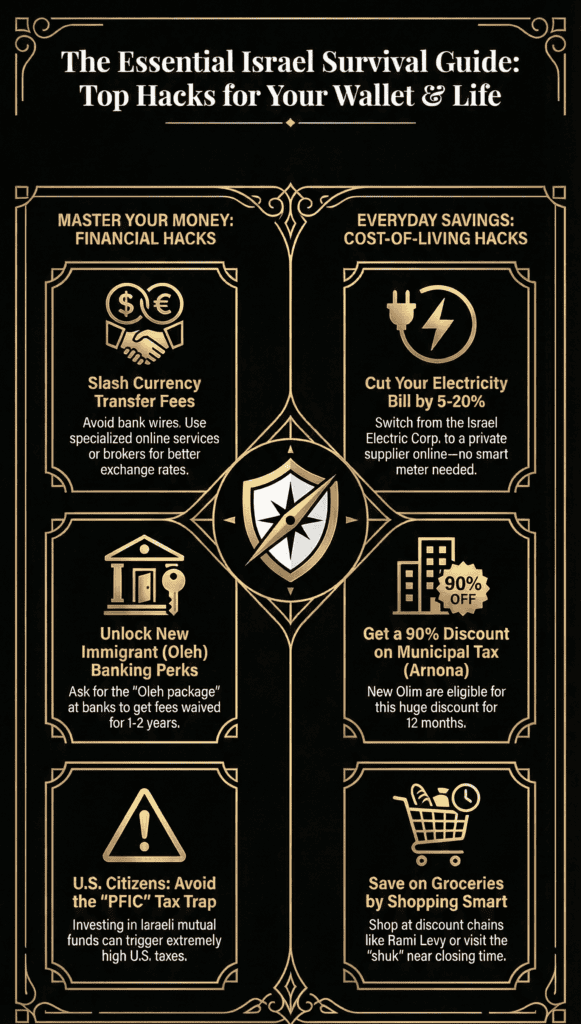
Israel offers meaningful tax benefits for new immigrants, especially around foreign-source income, but the details are changing and the paperwork matters. In general, new olim still have a 10-year exemption on foreign-source income, while new disclosure rules beginning January 1, 2026 require more reporting for those who become residents from that date. Government of Israel
Residency-date checkpoint (do not skip this):
- If your Israeli tax residency begins before January 1, 2026: you may fall under the prior reporting regime for the exemption period, but transitional rules can be nuanced.
- If your Israeli tax residency begins on or after January 1, 2026: plan for annual reporting of foreign income and assets even when tax-exempt, unless guidance for your category says otherwise. CWS Israel
What does the 10-year foreign-income benefit cover, and what does it not cover?
The classic “10-year benefit” is an exemption from Israeli tax on foreign-source income for qualifying new immigrants and certain returning residents. Foreign-source usually means the income is generated outside Israel (salary for work performed abroad, foreign dividends, foreign interest). It does not automatically exempt Israeli-source income, and it does not cancel tax obligations you still have in another country. Government of Israel
Define it in your own situation by asking one question: where is the work performed or where is the asset located? That is often what drives “source.”
Will you still have to report foreign income and assets during the holiday?
For residents who begin Israeli tax residency on or after January 1, 2026, published guidance indicates the foreign reporting exemption is being repealed. You may still receive the tax exemption on qualifying foreign-source income, but you can be required to disclose foreign assets and income to the Israeli Tax Authority. Dates matter, so confirm your status. CWS Israel
If you made Aliyah before that date, different transitional rules may apply, so do not guess.
Are there new 2026 incentives on Israeli-source income, and how should you treat the headlines?
The Tax Authority now provides an application service for temporary tax relief for qualifying new immigrants and veteran returning residents. Check the actual arrival window, income category, ceilings, application documents and any required approval with your tax adviser. This is separate from foreign-source income relief and does not remove an annual-return duty arising for another reason. Do not rely on an earlier news report describing only a proposal.
The practical takeaway: do not build a budget around a headline. Build it around confirmed guidance and a conservative estimate.
What should U.S. citizens and other dual taxpayers do differently?
If you still file taxes abroad, Israel’s exemptions do not cancel those obligations. Keep records that let you answer two systems: Israeli residency rules and your home-country reporting. Separate personal and business flows, track the source of each income stream, and get advice early if you have trusts, a company, or large investments.
Which government benefits matter most for your first-year cash flow?
The benefits that matter most are the ones that either put money into your bank account or reduce fixed bills you must pay anyway. For many new olim, that means Sal Klita payments, income tax credit points on Israeli earnings, and time-limited relief on specific costs. Timing is everything, and some benefits require an active Israeli account.
How does the Sal Klita absorption basket get paid, and what pauses it?
Sal Klita is an absorption grant paid in installments to help new immigrants settle, and the amount depends on your household profile. It is typically deposited into your Israeli bank account after you provide details. Official guidance notes that payments can pause if you leave Israel during the eligibility period, then resume when you return. Nefesh B’Nefesh
Action step: open the account early and submit your bank details as soon as you are instructed, so you do not delay the clock.
What other benefits can reduce big expenses in year one?
Beyond Sal Klita, new immigrants can qualify for income tax credit points on Israeli income for a defined period, with the government publishing an official breakdown by months after Aliyah. In addition, some olim receive limited-time relief tied to health system enrollment, and customs benefits can reduce duties on eligible personal goods and, in some cases, vehicles. Government of Israel
Do one thing that saves real money: print your benefits list, write the expiration dates next to each, and set calendar reminders 60 days before each deadline.
Quick view: income tax credit points for new immigrants
Nefesh B’Nefesh summarizes the credit-point schedule as follows (rules depend on your Aliyah date): Nefesh B’Nefesh
- Aliyah before January 1, 2022: 3 points for the first 18 months, 2 points for the next 12 months, and 1 point for the next 12 months (3.5 years total).
- Aliyah on/after January 1, 2022: 1 point for the first 12 months, then 3 points for 18 months, then 2 points for 12 months, then 1 point for 12 months (4.5 years total).
These points reduce Israeli income tax on Israeli-source earnings, so they matter most once you are working in Israel.
What is a realistic 30-day setup plan that keeps you liquid and lowers fees?
A realistic plan is one that assumes delays and still keeps you funded: arrive with a small shekel buffer, open an Israeli bank account quickly, and move bigger money only after you have a tested transfer method. Use day-to-day card spending to minimize cash handling, and schedule one larger conversion instead of many small ones that each trigger fees.
What should you do in the first 72 hours after landing?
Focus on functionality, not optimization. Get a local SIM, withdraw a modest amount of shekels from an ATM using a low-fee card, and book your bank appointment. If you have benefits that require a bank account, prioritize opening the account even if the bank’s app feels clunky. Keep every receipt and document in one folder from day one.
What should be in place by day 30?
By day 30, aim for: an active Israeli current account, online access, a debit card, and one inbound transfer route you have tested end-to-end. You should also know your tax and reporting status. Once those basics work, you can optimize: negotiate bank FX rates, use a licensed dealer, or choose fintech for recurring transfers.
When is it worth paying a professional, and which professional?
Pay for help when one mistake costs more than the fee: property sales, six-figure transfers, business setup, or multi-country taxes. An Israeli tax advisor can clarify residency, exemptions, and reporting, and a home-country specialist can keep you compliant there. Use a mortgage broker or planner for big shekel decisions, not for routine transfers.
Seven money rules for your first year in Israel
- Use the Bank of Israel representative rate as a reference, then compare the quoted net amount after all charges.
- Check card and ATM conversion terms and all issuer and operator charges before choosing the payment currency.
- For cash exchange, compare licensed changers and ask for the exact rate in writing. Government of Israel
- For large transfers, budget for the full wire cost stack: send fee, receive fee, and FX spread. Nefesh B’Nefesh
- Assume large transfers will trigger questions and prepare a source-of-funds folder before you move.
- Tax benefits are real, but 2026 disclosure rules and new incentives are date-dependent, so verify your status. Government of Israel
- Open your Israeli account early so benefits and salary payments do not get delayed. Government of Israel
Next step: open a notes file called “Israel Money Setup,” save your documents into one folder, and run one small test (ATM withdrawal or transfer) before you rely on it for a large move. One controlled test often saves weeks of frustration.
If you are planning to buy property in Israel, explore current homes for sale and our buyer guidance: browse Israeli homes for sale.
Thinking about your next move in Israeli real estate? Tell us what you are looking for and the Semerenko Group team will help.
Aliyah housing links for money-transfer planning
Currency timing is only one part of the move. Before transferring funds, connect the money plan to the property plan: the foreign-buyer guide, buying before Aliyah, the moving-to-Israel guide, and the rent-first framework for new olim.